

Cherry: The Smarter Way to Pay
Cherry Technologies, Inc.
- 4.5
- 50.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
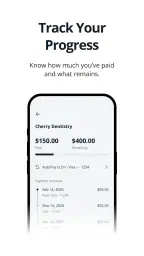
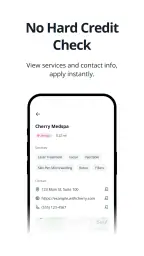
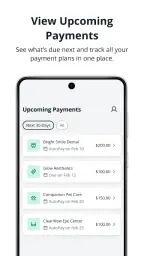
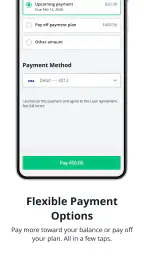
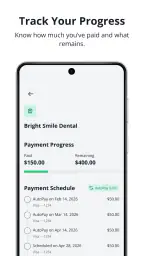
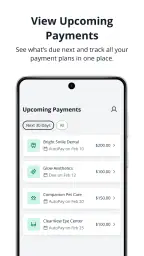
Cherry: The Smarter Way to Pay Pros and Cons
Pros
- Splits eligible purchases into manageable installments.
- Clear repayment schedule helps users plan monthly spending.
- May provide access to offers from participating retailers.
- Application streamlines checkout and payment management.
- Useful alternative for users avoiding traditional credit cards.
Cons
- Availability and terms may vary by country and retailer.
- Late or missed payments can lead to fees or account restrictions.
- Installment plans may encourage unnecessary spending.
- Not every purchase or merchant is eligible for financing.
- Approval decisions may depend on credit and personal information.
 Analysis by All-app
Managing a payment plan is one of those tasks that sounds simple until the due date arrives, the budget changes, or several purchases begin competing for attention. Cherry is a free finance app from Cherry Technologies, Inc. built around that specific problem: keeping plans together and paying according to a schedule that fits your situation. I found its appeal less in flashy extras and more in the way it gives a payment-focused task its own place instead of forcing it into a general banking app, notes app, or spreadsheet.
That focus matters if you regularly use payment plans and want a clearer view of what you have agreed to pay. It also creates an important question: how much control do you actually retain when an app is involved in something as sensitive as money? My assessment of Cherry is therefore not just about convenience. I looked at the practical workflow, the points where a user needs to make decisions, and the moments where I would personally slow down before confirming anything.
How Cherry fits into everyday payment planning
The app’s store summary is brief, but its purpose is easy to understand from use: it helps organize plans and lets you pay on your schedule. That makes it different from a traditional banking application, whose main job is usually to show account activity, transfer money, or manage a broader set of financial services. Cherry is more narrowly aimed at the payment-plan experience.
I can see the value on an ordinary payday. Imagine buying something through a plan and knowing that the first few days are easy to remember, but later payments may blend into rent, utilities, subscriptions, and card bills. Rather than relying on memory, I would use Cherry as the place to review that plan before deciding what to pay and when. The benefit is not that the app removes financial responsibility; it makes the responsibility more visible.
That distinction is important. I would not treat this as a replacement for a complete household budget. A budgeting app is usually better for comparing income with every category of spending, while a bank app remains the natural place to inspect balances and transactions across accounts. Cherry makes more sense as a focused layer for payment plans, especially when the usual alternatives feel too broad or too manual.
The app is free, carries an Everyone content rating, and requires Android 7.0 or later. Those details make it approachable for a wide range of Android users, including people using older compatible phones. It was released on February 20, 2026, and the current version is 1.3.0, so I would make a point of checking that the installed version is current before relying on it for an important payment routine.
Trust begins with a narrow, understandable purpose
Finance apps deserve a higher level of caution than entertainment apps because a small misunderstanding can have a real effect on someone’s money. Cherry earns some initial confidence from having a clear role rather than presenting itself as an all-purpose financial command center. When an app is focused on plans and scheduled payments, I find it easier to understand why I am opening it and what I expect to accomplish.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Its public reception is encouraging but still modest in scale: Cherry has an average rating of 4.5 from around 128 ratings, with about 50 written reviews and over 100K installs. I read that as a positive early signal, not as proof that every payment situation will work smoothly. A smaller review base can tell me that people are using the app, but it cannot replace my own careful checking of the payment details shown on screen.
The developer is clearly identified as Cherry Technologies, Inc., which is useful when deciding whether an app matches the service I intended to install. I would still verify the developer name before downloading, particularly when searching for a finance app with a short name that could be confused with unrelated products.
What I would check before connecting anything
My first trust habit with Cherry would be to read each permission and account prompt as it appears, rather than tapping through automatically. The app may need access related to its payment function, but I would not assume that every request is necessary simply because the app belongs in the finance category. The safest approach is to grant only what I understand and to pause when a request seems unrelated to managing a plan.
I would also inspect the account and security controls available during setup. A finance app should make it clear which account is being used, what payment action is about to happen, and how a user can review or change that choice. If I were setting Cherry up on a shared phone, a borrowed device, or a phone that might be lost, I would be especially careful about screen locks, sign-out options, and notifications that could reveal payment information.
Those are not minor details. A notification can expose a plan name or payment reminder to someone looking at a locked screen. I would adjust notification visibility at the operating-system level if the wording displayed more than I wanted others to see. I would also avoid entering financial information while connected to an untrusted public network, even if the app itself appears legitimate.
The payment screen is where attention matters most
The most important moment in Cherry is not opening the app; it is confirming a payment. Before I approve anything, I would check the plan identity, the amount, the destination, and the timing. A clean interface can make a transaction feel routine, but routine is exactly when mistakes happen. I would compare the information with the original agreement or purchase record instead of trusting my memory.
For someone managing several plans, I would use a simple personal naming habit wherever the app allows it: identify each plan by the purchase or purpose, not just by a vague merchant label. If Cherry presents plans in a fixed format that cannot be customized, I would keep a separate note with the matching purchase details. That small step reduces the chance of paying the wrong item when two plans look similar.
Another useful workflow is to review upcoming obligations before spending the rest of a paycheck. I would open the app at the same time I check my bank balance, then consider the scheduled payments alongside rent and recurring bills. Cherry can help make plan commitments visible, but I would not assume that the app has a complete picture of my finances unless the interface explicitly shows it.
Data-sensitive moments deserve a deliberate response
There are several points where I would be particularly alert: account creation, linking a payment method, changing a plan, and confirming a payment. These actions may involve sensitive financial information, so I would read the wording on each screen and look for an understandable explanation of what I am authorizing. If the app presents a choice, I prefer to make that choice consciously rather than accept a default.
I would also review the app’s privacy and data controls before adding more information than necessary. The safest personal workflow is to provide the details required for the task and avoid using free-text fields for unnecessary notes about income, family members, account numbers, or other private matters. If a note is useful, I would keep it short and practical.
Permissions should be revisited after installation, not only during setup. Android’s settings let me review and change access later, which is helpful if I initially granted something for convenience and then decided it was unnecessary. I would check those controls after the first successful payment and again after a major app update. That habit gives me a clearer sense of what I am allowing over time.
I would apply the same caution to support conversations and email. If I needed help with a payment, I would avoid sending full account details or screenshots containing sensitive information unless the official support process specifically required it and explained how to protect the data. A trustworthy user experience depends not only on the app’s visible screens but also on how carefully I handle information around it.
Where the app gives users agency
Cherry’s central promise is about paying on a schedule, and that naturally puts user agency at the center. I like the idea of reviewing a plan and making a payment decision when it suits my budget rather than treating every obligation as an invisible automatic event. Still, flexibility should never be confused with permission to ignore the original terms. I would read the plan conditions before changing timing or amount.
A practical way to use that flexibility is to set a personal review point before the payment becomes urgent. For example, I would check the plan after payday, when I know how much money is available, and then revisit it before the next major bill. This is more reliable than waiting for a reminder to force a last-minute decision. It also gives me time to investigate anything that looks unfamiliar.
I would want the app to make confirmation and cancellation choices unmistakable. If a button starts a payment immediately, the wording should be clear enough that I do not mistake it for a preview. If I change my mind, I would look for a visible way to back out before the final confirmation. When an app involves money, a deliberate pause is a feature in its own right.
Users should also retain control after a payment is made. I would review the resulting status, keep any available receipt or confirmation, and compare the transaction with my bank activity later. That second check is valuable because it separates “I tapped the button” from “the payment completed as expected.” If the app or the payment provider shows a pending state, I would avoid submitting the same payment again until I understand the status.
What works better than the usual alternatives
Compared with a spreadsheet, Cherry should be easier for a person who wants a dedicated payment-plan view without designing formulas, dates, and status columns. A spreadsheet can be more flexible, but that flexibility becomes work: I have to build it, maintain it, and remember to update it. Cherry is the more natural choice when the main task is reviewing and paying plans rather than analyzing spending patterns.
Compared with a banking app, Cherry’s narrower purpose can be an advantage. A bank application may show the final transaction, but it may not present the plan itself in the way I need to think about it. On the other hand, my bank remains better for checking whether money actually left the account and for seeing the wider effect on my balance. I would use the two together rather than expecting one to replace the other.
Compared with a calendar reminder, Cherry can be more useful at the moment of payment because a calendar only tells me that something is due. A reminder cannot normally verify the plan details or guide the payment action. Yet a calendar still has a role: I might use it as an independent prompt, especially for a high-value obligation, so that one missed notification does not become a missed payment.
Compared with a full budgeting application, Cherry is less suitable for deciding whether I can afford a purchase in the first place. A budget needs income, essentials, savings goals, debt, and irregular expenses. Cherry is better after a plan exists, when the question is how to keep track of it and make the next payment responsibly. That boundary is one of the most important things to understand before installing it.
Small workflows that make it more dependable
I would begin with one plan and learn the app’s labels before adding more. That makes it easier to recognize what each status means and to notice whether the payment flow matches my expectations. Adding everything at once may save a few minutes, but it makes troubleshooting harder if one entry looks wrong.
My second tip is to create a brief monthly review rather than relying entirely on notifications. I would check active plans, upcoming decisions, completed payments, and any item that remains pending. This catches stale information and helps me spot a plan that I no longer recognize. It is also a useful time to review permissions and notification privacy.
My third tip is to keep an independent record of important confirmations. I would save the date, amount, and plan reference in a secure place, without copying unnecessary sensitive information. That record can help me compare the app with my bank statement and resolve confusion later. It also protects me from depending on a single screen for the entire history of a financial commitment.
Finally, I would not use a payment-plan app as a reason to stretch my budget. The ability to pay according to a schedule can make a purchase feel more manageable while still representing a real obligation. Before accepting a new plan, I would add its expected payments to my existing commitments and ask whether the total remains comfortable if an unexpected expense appears.
Who should use it and who should look elsewhere
Cherry is a good fit for someone who already has payment plans and wants a focused way to review them. It may also suit users who find spreadsheets too fiddly and general banking apps too broad. The free price lowers the barrier to trying it, and the Everyone rating makes it approachable for a broad audience, subject to the device requirement.
I would be more cautious about recommending it to someone who wants complete financial planning, investment tracking, detailed expense categorization, or a single dashboard for every account. Those needs call for a broader finance tool. I would also suggest skipping it if the user is uncomfortable reviewing payment terms or account prompts independently; no app can make a financial decision safe when the person approving it has not checked the details.
People who share devices should think carefully before using it. I would prefer a personal, protected phone and would review notification previews before adding payment information. Anyone managing plans for another person should also confirm whose account is connected and who has authority to approve payments. Convenience is not worth creating ambiguity about ownership or consent.
My cautious verdict after using the workflow
Cherry’s strongest quality is its focused role. It gives payment plans a dedicated home and encourages me to treat them as active commitments instead of background promises. I appreciate that this can sit between a broad budgeting tool and a bank account: more purposeful than a note, but not pretending to be my entire financial life.
The limitations are equally important. I would still verify every payment against the original terms, confirm the destination and timing, and check the bank afterward. I would not assume that a polished payment screen tells me everything about affordability, privacy, or long-term account management. The app is most useful when paired with those habits, not when used as a substitute for them.
With an average rating of 4.5 and more than 100K installs, Cherry has attracted meaningful early attention, while its current version, 1.3.0, suggests an actively evolving product. My recommendation is measured: try it if your main problem is organizing payment plans and making deliberate payments, but keep your bank app or budget system involved for verification and broader context.
My bottom line: Cherry is worth considering for focused payment-plan management, especially if you value a clear, schedule-oriented workflow. I would install it with permission awareness, test it with a single plan, and make user control the deciding factor at every sensitive step. If it helps you see commitments more clearly without encouraging careless spending, it can earn a useful place in your financial routine.
Frequently Asked Questions
What is Cherry: The Smarter Way to Pay?
Cherry is a payment and financing platform that allows customers to split eligible purchases into scheduled installments instead of paying the full amount upfront. It is commonly offered by participating merchants for services and products, particularly in areas such as healthcare, wellness, beauty, and elective treatments. Available plans, approval decisions, repayment terms, and total costs can vary depending on the merchant and the customer’s application.
How does Cherry financing work?
After selecting Cherry at a participating checkout, you typically provide personal and financial information so the service can review your application. If approved, Cherry presents one or more payment plans with details such as installment amounts, repayment frequency, and any applicable fees or interest. You should carefully review the agreement before accepting, because the final terms depend on your credit profile, the purchase, and the merchant’s available financing options.
Does using Cherry require a credit check?
Cherry may use information from your application and, depending on the financing product and circumstances, may perform a credit-related review. The effect on your credit profile can differ between an initial eligibility check and a completed financing application. Approval is not guaranteed, and submitting an application does not necessarily mean every merchant or purchase will qualify. Read the disclosures shown during the application process for the most accurate information.
Are there fees or interest charges when paying with Cherry?
Costs depend on the specific plan offered to you. Some options may advertise promotional or low-cost financing, while others can include interest, service charges, late fees, or other expenses. The amount displayed at checkout may not tell the entire story, so check the annual percentage rate, total repayment amount, payment schedule, and consequences of missed payments before confirming. Terms may also differ by merchant and location.
What happens if I miss a Cherry payment or need help with my plan?
Missed payments can potentially result in late charges, account restrictions, collection activity, or negative credit reporting, depending on the agreement and applicable laws. If you expect difficulty making a payment, contact Cherry through the app or official support channels as soon as possible rather than ignoring the issue. The app may help you view upcoming installments, manage payment methods, and review account information, but it does not automatically change your contractual obligations.


